Wealth Management and Financial Planning: Where the Line Actually Sits
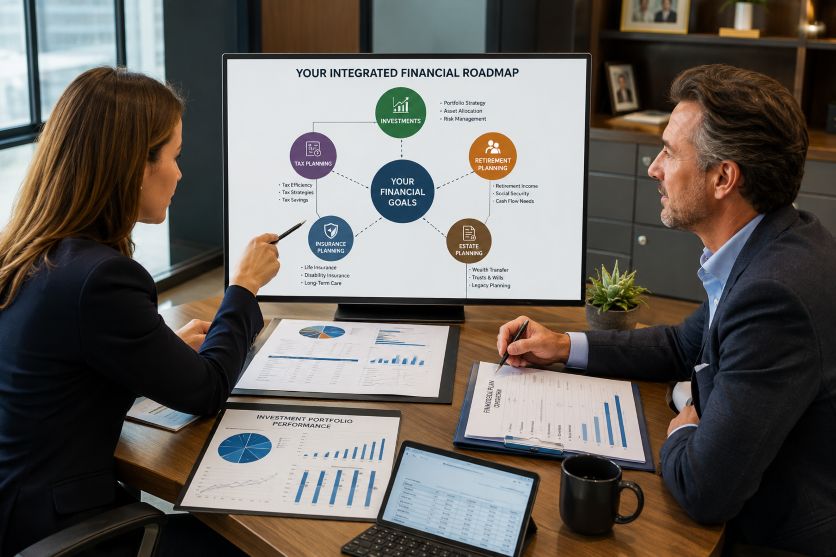
Financial decisions rarely exist in isolation. Saving for retirement, protecting assets, investing wisely, preparing for taxes, and transferring wealth to future generations all influence one another. Research from CFP Board and guidance published by Financial Planning Standards Board (FPSB) show that effective financial decision-making works best when individual goals are connected through an organized planning process rather than treated as separate tasks.
Confusion often arises because the terms wealth management vs financial planning are frequently used interchangeably. Although they overlap in many areas, they describe different scopes of service. Understanding where each one begins and ends helps individuals choose the type of professional support that best matches their financial situation and long-term objectives.
Why the Two Terms Are Often Confused
Financial planning and wealth management share many common elements. Both focus on helping people make informed financial decisions, prepare for future needs, and reduce unnecessary financial risks. Because investment advice often appears alongside retirement planning or tax discussions, many people assume the services are identical.
Experts at the Financial Planning Association (FPA) explain that financial planning centers on identifying goals, evaluating financial circumstances, and creating practical strategies for achieving those goals. Wealth management generally builds upon that foundation by coordinating several specialized financial disciplines into a broader long-term strategy.
The distinction becomes more noticeable as financial situations become increasingly complex. Individuals with growing investment portfolios, business ownership, multiple income sources, or estate planning considerations often require coordination that extends beyond a traditional financial plan.
Financial Planning Focuses on Personal Goals
Financial planning begins with understanding what someone wants to accomplish. Those objectives may include buying a home, saving for education, reducing debt, preparing for retirement, or creating emergency savings.
Professionals typically gather information about income, expenses, assets, liabilities, insurance coverage, and future priorities before recommending a structured action plan. The process is highly personalized because every household faces different opportunities and constraints.
Typical components of financial planning include:
- Budgeting and cash flow management
- Debt reduction strategies
- Retirement savings projections
- Education funding plans
- Risk assessment
- Basic insurance reviews
- Goal-based investment recommendations
Standards developed by the Financial Planning Standards Board (FPSB) emphasize that planners should regularly review and update recommendations as personal circumstances change. Marriage, career changes, children, or unexpected financial events often require adjustments to previously established plans.
Wealth Management Takes a Broader Perspective
Wealth management expands the conversation beyond individual financial goals. Rather than focusing on one planning area at a time, it coordinates multiple financial disciplines into a unified long-term strategy.
This broader approach frequently combines investment management, tax planning, insurance evaluation, estate planning, charitable giving strategies, business succession planning, and retirement income planning. The objective is to ensure each area supports the others rather than creating unintended conflicts.
Reports from CFA Institute note that comprehensive wealth management increasingly emphasizes integrated advice because investment decisions often carry tax consequences, insurance needs influence estate planning, and retirement strategies affect long-term income planning.
Someone approaching retirement, for example, may need guidance on portfolio withdrawals, tax-efficient income, healthcare costs, estate documentation, beneficiary designations, and insurance adjustments. Handling each issue independently may produce inconsistent results, while coordinated planning can improve overall financial efficiency.
Comparing the Two Approaches
Primary Objective
Financial planning primarily helps individuals identify, prioritize, and achieve specific financial goals.
Wealth management focuses on coordinating every major financial decision throughout an individual’s lifetime.
Typical Scope
A financial plan often addresses budgeting, retirement, education savings, debt reduction, and investment recommendations that support defined objectives.
A wealth management strategy may include investment oversight, tax efficiency, estate coordination, insurance analysis, philanthropic planning, and business succession where appropriate.
Who Typically Benefits
Financial planning serves individuals and families across many income levels because nearly everyone benefits from structured financial decision-making.
Wealth management often becomes increasingly valuable for people with larger investment portfolios, business interests, multiple properties, complex tax situations, or multigenerational wealth considerations.
Why Neither Approach Replaces the Other
The debate sometimes suggests that one service is more comprehensive or more valuable than the other. That comparison overlooks how the two approaches naturally complement one another.
A financial plan frequently serves as the foundation upon which broader wealth strategies are built. Clear financial goals provide direction for investment decisions, tax planning, insurance coverage, and estate arrangements. Many of the same principles discussed in how financial planning works in a company demonstrate how coordinated planning creates stronger decision-making by aligning financial objectives with long-term strategy. The same concept applies to personal finances, where clear priorities help every financial discipline work together more effectively.
Likewise, wealth management helps ensure individual recommendations continue working together as financial circumstances evolve. Life events rarely affect only one part of someone’s finances. A business sale, inheritance, retirement, or relocation often influences taxes, investments, insurance needs, and estate planning simultaneously.
Studies published by OECD consistently show that improving financial capability involves combining financial knowledge with ongoing planning and periodic review rather than making isolated financial decisions.
How Needs Change Over Time
Financial priorities evolve throughout every stage of life. Young professionals may focus primarily on debt reduction and emergency savings. Families often shift attention toward education funding, insurance protection, and retirement accumulation. Later years introduce questions about retirement income, healthcare costs, tax efficiency, and wealth transfer.
Findings from World Bank research highlight that long-term financial resilience depends on adapting strategies as household circumstances change rather than relying on a fixed plan created years earlier.
This gradual evolution explains why many people begin with financial planning and eventually require broader coordination. The transition reflects increasing complexity rather than replacing one service with another.
Conclusion
Financial planning and wealth management should be viewed as complementary parts of a complete financial journey. One establishes meaningful goals and creates practical roadmaps. The other coordinates investments, taxes, insurance, estate considerations, and long-term decision-making so every element works together.
As personal finances become more complex, maintaining that coordination becomes increasingly valuable. Whether someone is just beginning to organize their finances or managing multiple financial priorities later in life, understanding the distinct roles of each approach helps create clearer expectations and more informed decisions for the future.


 Finance plays a major role in how outdoor spaces are designed. Homeowners and developers now look beyond visual appeal. They want outdoor areas that add real value. Every design choice is often reviewed with cost and long-term use in mind.
 Seoul and other major cities can be expensive, especially when it comes to rent, transportation, and dining out. Rent for a one-bedroom apartment in Seoul can range from 500,000 to 1,500,000 KRW per month, depending on the location and type of lease agreement. Jeonse, a lump-sum deposit rental system, is common and requires a substantial upfront payment but reduces monthly rent costs.
 Fighting over money as a married couple is never a picnic. Seeking advice from financial advisers or accountants would be a big help, especially if you are already headed down a rough road. A solid financial strategy and budget can be developed through their collaborative effort.





 Since many consumers now use mobile phone apps as ewallets, entrepreneurs who want to keep payment methods simple ask if having a bank account is still relevant? The answer of course is yes, maintaining a bank deposit account is still relevant and in certain cases a business requirement.
 A business organization registered as a Limited Liability Company (LLC) or as a corporation is required to maintain a bank account. A business bank account serves as a means of maintaining control over the funds derived from business operations and over payments of business expenditures and obligations.
 An entrepreneur will find it easier to organize and manage finances because banks provide a breakdown of transactions related to the movement of funds held in a bank account. Actually it simplifies the bookkeeping process, especially for taxation purposes.
 For a business’s or company’s marketing plan and efforts to be effective and successful, adaptation to what works now is essential. For different marketing avenues like traditional media (TV, radio, print publications) and digital media (email, social media, website), what might have been very effective years ago may not be practical, worthwhile or relevant today.
 Search Engine Optimization For Financial Services
 Fortunately, there are financing companies that offer financing solutions for such purposes.
 Typically, the requested funding will be used to pay a Vendor or Supplier who is in the business of wholesale trading or manufacturing. In some cases, a merchant needs financing to pay a technology or marketing service provider.
 A successful ecommerce website is mobile-friendly in the sense that online shoppers can browse, shop and pay for purchases straight form their smartphone or tablet with practically zero hassle. Recent studies show that this is the most important aspect as about 61% of online shoppers prefer using their mobile device when shopping online. A mobile-friendly store means everything displayed on the screen of their mobile device can be viewed in the appropriate screen size.

